

A low appraisal can stall a closing overnight, but buyers usually have more leverage than they realize, from disputing the value to restructuring the loan itself. Whether you’re weighing a Reconsideration of Value request, exploring gap financing, or wondering if a different lender might handle the same appraisal differently, the resource you pick matters. This list compares the broker and lender options worth evaluating, based on how each handles reconsideration-of-value requests, program flexibility, and gap financing.
Quick Comparison
- Mortgage Mastermind: best for buyers who want multiple loan programs or lenders to choose from after a low appraisal; quote-based pricing; the only option here that shops hundreds of wholesale lenders instead of one in-house rate sheet.
- Rocket Mortgage: best for buyers who want a fast, self-serve digital process for filing the dispute themselves; quote-based pricing; the only lender here with a fully online ROV submission portal.
- Veterans United: best for veterans facing a low VA appraisal; quote-based pricing; the only lender here built around VA Tidewater Initiative expertise.
- Guild Mortgage: best for buyers who may need down payment assistance to bridge the gap; quote-based pricing; the only lender here with broad down payment assistance program partnerships.
- Movement Mortgage: best for buyers on a tight timeline; quote-based pricing; the only lender here emphasizing compressed in-house processing to speed up a second appraisal opinion.
- NFM Lending: best for buyers who want to switch loan programs without switching lenders; quote-based pricing; the only lender here offering in-house FHA, VA, USDA, and conventional programs to pivot between.
1. Mortgage Mastermind
Mortgage Mastermind is a mortgage brokerage led by Duane Buziak that shops hundreds of wholesale lenders and multiple loan programs, which matters most in the days after an appraisal comes in short. Instead of being stuck with one underwriting guideline and one appraisal review process, buyers working with a broker can pivot to a different wholesale investor whose loan-to-value requirements or reconsideration process may fit the situation better.
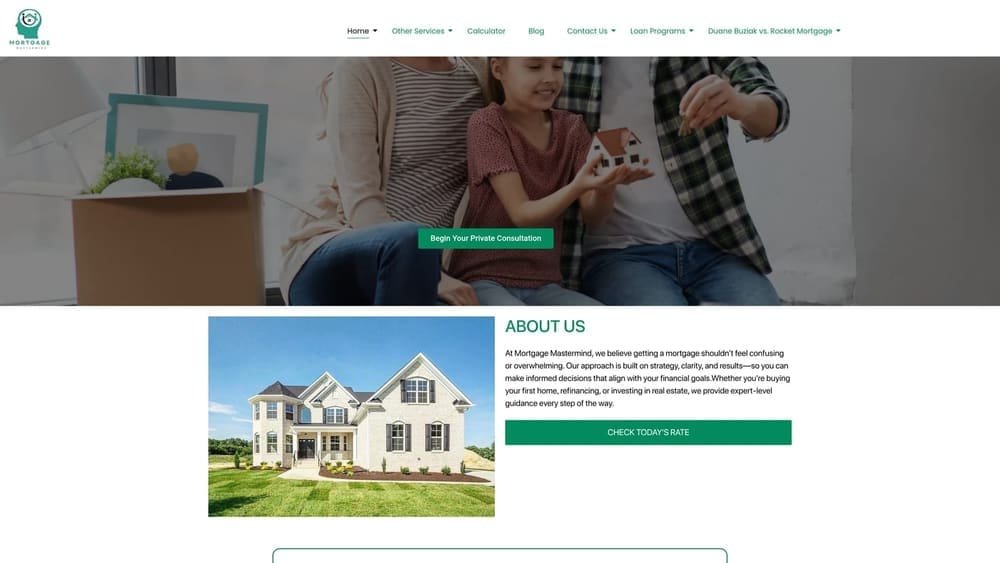
The distinction here is structural. A direct lender reviews an appraisal against its own single rate sheet. A broker can move the file to a different wholesale lender entirely if one investor’s guidelines don’t leave room to flex. That gives a buyer facing a low appraisal more paths forward than a rebuttal letter to the same underwriting desk.
- Access to hundreds of wholesale lenders with differing appraisal review standards, so a denial from one guideline doesn’t end the loan
- Credit-safe pre-qualification that lets buyers explore alternate loan programs without a hard inquiry on every option
- Connections to realtors, title, and insurance professionals who can help renegotiate price or terms alongside the financing conversation
- Licensing across Virginia, Florida, Tennessee, Georgia, DC, North Carolina, South Carolina, and Maryland for buyers relocating or investing across state lines
Setup is consultative rather than app-only: a loan officer walks through the appraisal, the comparable sales it used, and which programs or lenders might treat the value differently. That’s a strength for buyers who want a second opinion and a weakness for anyone who wants an instant, fully automated online closing with no conversation at all. Pricing is quote-based, since rates and fees vary by the wholesale lender and loan program ultimately selected.
Best for: Buyers who want to explore multiple loan programs or lenders after an appraisal comes in low.
2. Rocket Mortgage
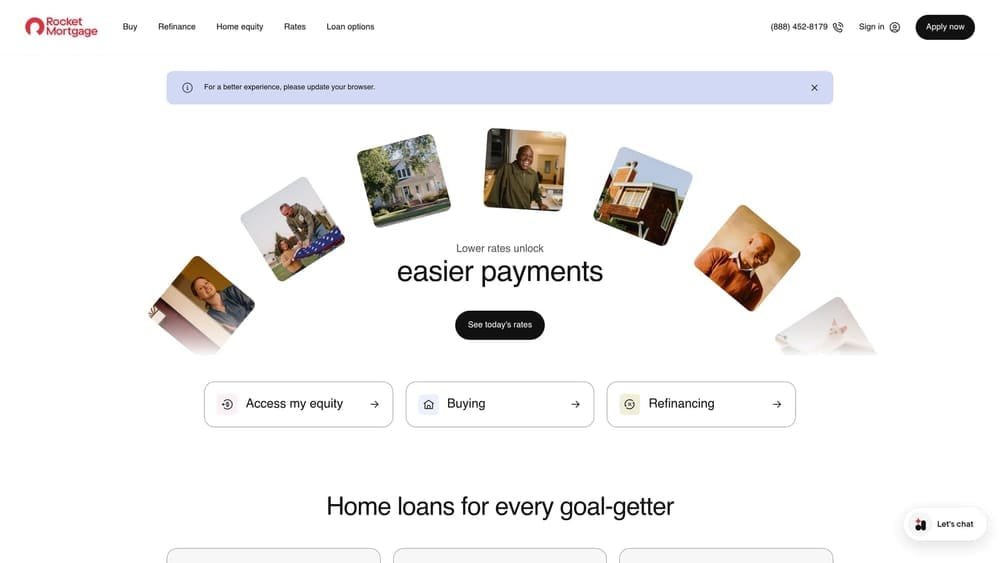
Rocket Mortgage is a large national direct lender built around a fully digital application and document process, and that extends to how it handles appraisal disputes. Buyers who receive a low value can submit supporting documentation for a reconsideration request directly through Rocket’s online portal rather than emailing a loan officer or mailing paperwork.
Its main features include:
- Digital submission of Reconsideration of Value documentation through the borrower’s online account
- In-house underwriting that keeps the loan file and the appraisal dispute in one system
- A proprietary appraisal management company panel that assigns and tracks the appraiser
- A range of conventional, FHA, and VA loan options available without switching institutions
Because Rocket operates on a single internal rate sheet, a denied ROV doesn’t open the door to a different underwriting guideline internally. If the dispute fails and the buyer wants to try a different loan program with different appraisal tolerances, that typically means starting a new application with another lender. The process is self-directed: borrowers largely manage document uploads and status checks themselves through the portal, which suits buyers comfortable handling the dispute with minimal hand-holding. Pricing is quote-based; check the site for current rates.
Best for: Buyers who prefer a fast, app-based process for handling the appraisal dispute themselves.
3. Veterans United
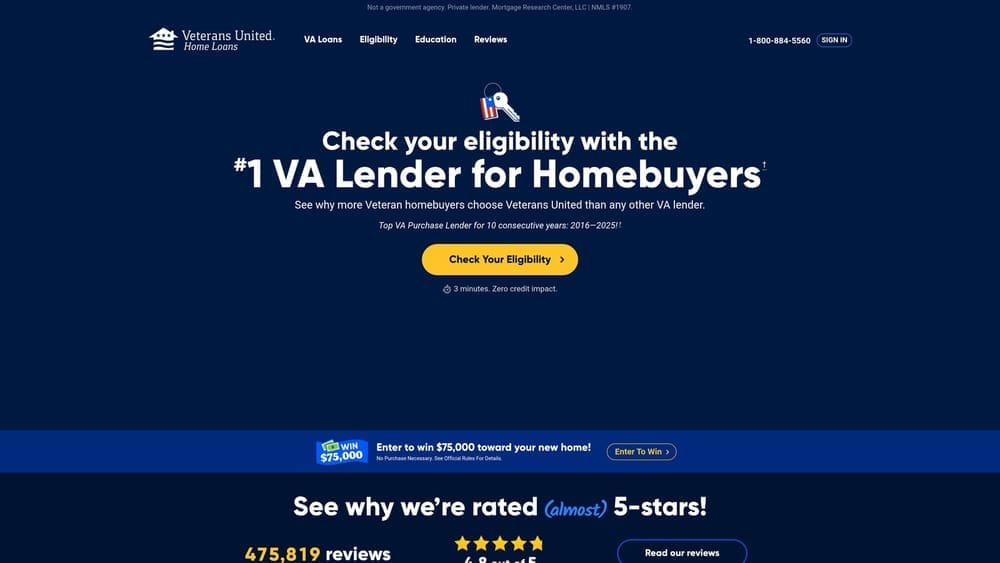
Veterans United is a VA loan specialist lender, and that focus is especially useful when a VA appraisal comes in low, because the VA has a formal process for this exact scenario. The Tidewater Initiative allows the borrower’s agent or lender to submit additional comparable sales before the appraiser finalizes the Notice of Value, which is a narrower and faster window than a standard post-appraisal rebuttal.
Why the VA-specific angle matters
Loan officers and processors who work VA files daily tend to know the Tidewater timeline cold: how many days the appraiser has to consider new comps, what documentation carries weight, and how to coordinate with the listing and buyer’s agents to gather it quickly. That familiarity can be the difference between a successful mid-process correction and a value that’s already locked in.
- Loan officers and processors focused specifically on VA transactions
- Working familiarity with the Tidewater Initiative timeline for pre-final value disputes
- Dedicated staff for entitlement, eligibility, and VA-specific loan questions
- Support materials tailored to VA appraisal and inspection requirements
The tradeoff is scope. A conventional or FHA buyer facing a low appraisal won’t find the same depth of resource here, since VA loans are the core business rather than one product among many. Pricing is quote-based; see the site for current VA rates.
Best for: Veterans and service members facing a low VA appraisal who want Tidewater-specific guidance.
4. Guild Mortgage
Guild Mortgage is a retail lender with local loan officers, and one advantage in a low-appraisal scenario is its access to a range of down payment assistance program partnerships. When renegotiating the sale price isn’t realistic and the buyer doesn’t want to dispute the value, closing the gap with additional funds is sometimes the more practical route, and Guild’s local officers can help identify which assistance programs the buyer may qualify for.
Its core offerings include:
- Local loan officer support for assembling appraisal rebuttal documentation
- Access to multiple down payment assistance program partnerships that can offset an appraisal gap
- In-house underwriting across conventional, FHA, and VA loan products
- A retail branch presence across multiple states for in-person conversations
Because underwriting and appraisal review sit on one in-house rate sheet, Guild’s flexibility is bounded by its own guidelines. If that guideline doesn’t allow enough room to work with, the borrower doesn’t have an easy way to pivot to a different investor within the same application. Setup involves working with a local branch loan officer who manages the file day to day, which suits buyers who prefer an in-person relationship over a purely digital one. Pricing is quote-based; see the site for current rates.
Best for: Buyers who may need down payment assistance to close the gap left by a low appraisal.
5. Movement Mortgage
Movement Mortgage is a national retail lender known for compressed in-house processing timelines. When a low appraisal triggers the need for a desk review or a second appraisal opinion, speed matters, especially if the purchase contract has a tight closing deadline or appraisal contingency window.
- Streamlined in-house processing and underwriting designed to move files faster than average
- A retail branch network across multiple states for local support
- Support for conventional, FHA, and VA loan programs under one roof
- A community-oriented service model with a dedicated loan officer as the point of contact
The limitation is the same structural one that applies to any single-shelf lender: Movement’s underwriting sits on its own rate sheet, so if a reconsideration request is denied, the buyer’s next move is typically a new application with a different lender rather than an internal guideline shift. Day-to-day, the file is run by an assigned loan officer and processor, which keeps the dispute process centralized but limited to what Movement’s own appraisal panel will accept. Pricing is quote-based; see the site for current rates.
Best for: Buyers on a tight timeline who want the fastest possible internal review after a low appraisal.
6. NFM Lending
NFM Lending is a retail lender with an in-house menu of FHA, VA, USDA, and conventional loans, and that breadth is useful after a low appraisal because different programs carry different loan-to-value and appraisal tolerance rules. A buyer who doesn’t qualify under a conventional guideline after a low value might find more room under an FHA or USDA structure, without needing to switch lenders entirely.
- In-house access to FHA, VA, USDA, and conventional loan programs under one lender
- Retail loan officers who work appraisal disputes directly with the assigned appraisal management company
- Multiple program options with different LTV and appraisal requirements to try if one doesn’t work
- A regional branch network for local, in-person loan officer relationships
The catch is that this flexibility is still confined to one underwriting shelf. Switching from a conventional program to an FHA or USDA program within NFM only helps if NFM’s own guidelines for that program accommodate the appraised value; it doesn’t open the door to a wholesale marketplace of outside investors with their own separate standards. A retail loan officer manages the file and appraisal conversation directly, which keeps communication straightforward but bounded. Pricing is quote-based; see the site for current rates.
Best for: Buyers who want to try a different loan program with the same lender after a low appraisal.
Matching Your Situation to the Right Path
Veterans facing a low VA appraisal should start with the Tidewater route through a VA-focused lender like Veterans United, since that process has a narrow window to submit new comparable sales before the value is finalized. Buyers who want maximum flexibility, whether that means trying a different loan program, a different wholesale lender, or renegotiating terms with the seller, are generally better served by a broker who can shop multiple lenders rather than working within one institution’s rate sheet. Those who prefer a single point of contact and a familiar in-house process may lean toward a retail lender’s own dispute process instead.
None of these paths guarantee a different outcome. Appraisal reconsiderations succeed or fail based on the specific report, the comparable sales used, and whether new data genuinely supports a higher value, not on which lender is asked to review it. What changes is how much room you have to maneuver if the first answer isn’t the one you needed.
Ready to experience the award-winning service that earned us VA Broker of the Year and recognition as a top 1% nationwide mortgage broker? Schedule your no-pressure consultation today and discover how our customized financing strategies across VA, FL, TN, and GA can help you achieve your homeownership or investment goals with credit-safe inquiries and expert guidance every step of the way.
