

This comparison is for borrowers carrying, or about to take on, a mortgage rate that feels too high: homebuyers weighing a purchase, owners considering a refinance, and veterans with an older VA loan. The options below are the lenders Duane Buziak compared on how many loan programs they access, whether they can price a file against more than one rate sheet, how they handle credit inquiries, and what they offer rate-sensitive buyers. The focus is structure, because no lender can change the market, but how a lender is built changes how many prices you see.
Quick Comparison of the Six Options
- Mortgage Mastermind by Duane Buziak: borrowers who want several lender prices compared before committing; quote-based pricing; shops hundreds of wholesale lenders with a soft-pull pre-approval first.
- Rocket Mortgage: borrowers who want a self-serve online process; quote-based pricing; digital application at national scale with in-house servicing.
- Veterans United Home Loans: veterans and service members; quote-based pricing; a lending focus built around VA loans.
- Guild Mortgage: first-time buyers who want in-person help; quote-based pricing; branch loan officers who know local assistance programs.
- Movement Mortgage: borrowers who want one national retailer with a relationship-based process; quote-based pricing; retail loan officers paired with in-house underwriting.
- NFM Lending: borrowers who want a branch-based officer and one more quote to compare; quote-based pricing; branch-level loan officers across a broad product menu.
1. Mortgage Mastermind by Duane Buziak
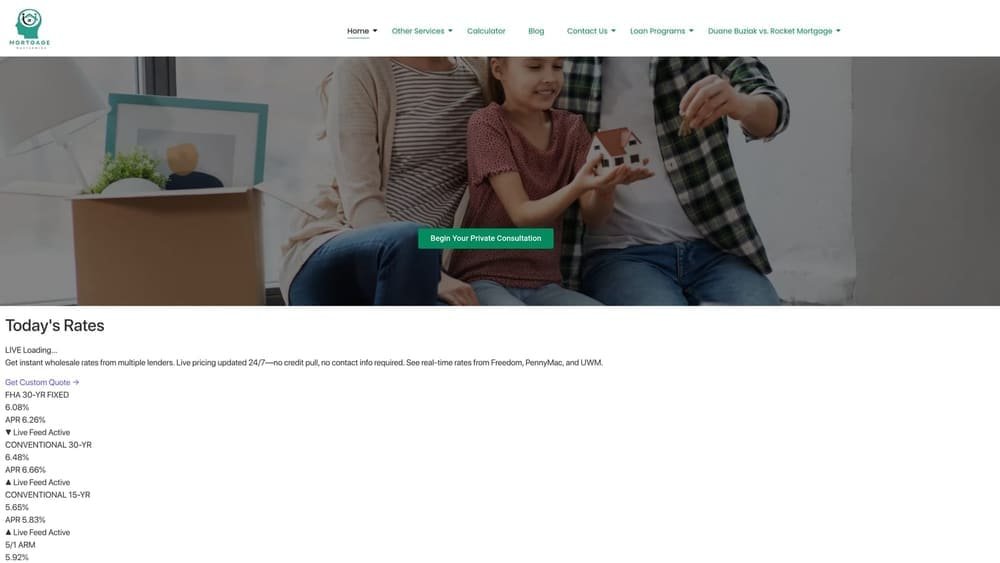
Mortgage Mastermind by Duane Buziak is a broker-plus-lender operation, which means Duane Buziak can place a file with hundreds of wholesale lenders instead of pricing it off one internal rate sheet. It covers purchase, refinance, VA, USDA, renovation, commercial, and specialized lending, and it is built for borrowers who want to see several prices before they commit.
- Access to hundreds of wholesale lenders, so a rate that looks high from one lender can be tested against others.
- NoTouch Credit Pull, a soft-pull pre-approval that lets you see options without a hard inquiry up front.
- VA, USDA, renovation, commercial, and specialized programs under one roof, which helps when a file does not fit a standard box.
- Connections to realtors, title, and insurance services, which can trim other costs around the loan.
- A zero-pressure, customized strategy rather than a single canned product.
An illustration, not a quote: suppose you borrow $400,000 over 30 years. At 7.00% the principal and interest payment is about $2,661 a month. If a second wholesale rate sheet prices the same file at 6.75%, the payment is about $2,594, a difference of roughly $67 a month, or about $24,000 over 30 years if you keep the loan that long. Alternatively, a discount point (prepaid interest, 1% of the loan, here $4,000, that buys a lower rate) taking you from 7.00% to 6.75% would break even in about 60 months. A lender credit works in the opposite direction: you accept a slightly higher rate and the lender offsets closing costs. A broker can lay out all three paths side by side.
The limits are real. Licensing covers only VA, FL, TN, GA, DC, NC, SC, and MD, with South Carolina handled on a broker-only basis, so borrowers elsewhere need another option. Shopping more sheets improves your odds, but nobody can guarantee the lowest rate on any given day. Pricing is quote-based and moves with credit profile, down payment, program, property type, and loan size.
Best for: Borrowers who want multiple lender prices compared before committing.
2. Rocket Mortgage
Rocket Mortgage is a large national direct lender known for a digital application and for underwriting and servicing loans in-house. It deserves credit for making the process fast and self-directed, which suits borrowers comfortable doing most of the work online.
Its distinctive strength on this list is scale combined with a fully digital, self-serve flow. You can start an application, upload documents, and track progress without much phone time. Its menu has included purchase and refinance loans across conventional, FHA, VA, and jumbo options, though you should verify the current program list on its site as of publication, since offerings change.
The structural trade-off is that you receive one lender’s pricing. There is no side-by-side wholesale comparison inside the company, so the only way to know whether its offer is competitive is to get other quotes. That is where the Loan Estimate matters: a standardized three-page form that lenders must provide after you apply, which lets you compare rate, points, and fees line by line. The CFPB explains how to read it on its Loan Estimate page.
- Online application that moves you from start to pre-approval without branch visits.
- In-house underwriting and servicing, so one company handles the file from application to monthly payments.
- Purchase and refinance options for borrowers who want to stay with one lender through a rate-driven refinance later.
Setup is mostly self-managed, and there is little to integrate; check the website for current partner details. It suits borrowers who value convenience and are willing to collect a competing quote on their own. It is less suited to anyone whose main goal is comparing several lenders’ prices in one conversation, or whose file needs hands-on structuring. Pricing is quote-based and varies with credit score, down payment, loan type, and property.
Best for: Borrowers who prioritize an online, self-serve experience.
3. Veterans United Home Loans
Veterans United Home Loans concentrates on military and veteran borrowers, and that focus is its defining strength. Few lenders on this list build their whole process around VA lending, including educational resources written for veterans who are buying for the first time.
The IRRRL for Veterans With a High Rate
If your current loan is already a VA loan, the Interest Rate Reduction Refinance Loan (IRRRL, often called a VA streamline) is the tool built for lowering the rate or payment. The VA describes the program and its funding fee on its IRRRL page, and fee details on its funding fee page. The loan generally requires a benefit to you, such as a lower rate or payment, so refinancing only makes sense when the numbers show it. Veterans United offers VA refinance options including the IRRRL; verify its current details as of publication.
- VA purchase loans for veterans, service members, and eligible borrowers.
- VA refinance options, including the IRRRL, for owners with existing VA loans.
- A veteran-focused process, so staff are used to entitlement and certificate questions.
- Educational resources that explain VA benefits before you apply.
The limitation is twofold. Because the company is veteran-focused, it is a narrower fit for borrowers without VA eligibility. And even for veterans, you receive one lender’s VA pricing, so the same advice applies: get a second quote, since VA loan pricing varies between lenders. Setup is online and phone-based, and a loan team runs the file; see the website for partner details. Pricing is quote-based, driven by credit, loan amount, down payment, and, on VA loans, the funding fee category.
Best for: Veterans and service members seeking a VA-specialist lender.
4. Guild Mortgage
Guild Mortgage is a national retail lender that works through local loan officers and branches. For borrowers who want to sit across a desk from someone who knows the neighborhood’s programs, that structure is the draw.
Its distinctive advantage here is local assistance-program knowledge. A branch-based officer often knows which down payment assistance options exist in a market and how they layer with a first-mortgage product, though availability varies by market, so verify what is open to you. Reported product coverage includes FHA, VA, USDA, and conventional loans for purchases and refinances; confirm the current menu on its website as of publication.
For rate-sensitive buyers, one tool worth asking any lender about is a temporary buydown: money, often from a seller or builder, that lowers your rate by a set amount in the early years (a 2-1 buydown cuts it by 2 points in year one and 1 point in year two), after which the note rate applies. It eases early payments but does not change the permanent rate, so qualify at the note rate. Ask whether and how a given lender supports it.
- Local loan officers who can walk a first-time buyer through each step in person.
- Purchase and refinance loans across several government and conventional programs.
- Down payment assistance support in markets where programs exist.
The limitations are structural. Guild works from its own rate sheet, so you see one lender’s price, and branch presence and program availability vary by market. Day-to-day, your loan officer and a processing team run the file, and setup is a conversation rather than a self-serve flow. It is a weaker fit for borrowers whose priority is comparing many lenders in one pass, or for those in areas without a nearby branch. Pricing is quote-based and moves with credit, down payment, program, and property.
Best for: First-time buyers wanting in-person local guidance.
5. Movement Mortgage
Movement Mortgage is a national retail lender that pairs loan officers with in-house underwriting and servicing. Its model is relationship-driven: you work with a loan officer, and the company handles processing and underwriting internally rather than passing the file around.
The in-house approach can make communication simpler, because the people processing your loan sit inside the same company as the officer who quoted it. That is its standout compared with the list: a relationship-focused retail experience with direct control over processing, at national scale.
Limitations start with pricing. It is a single-lender rate sheet, so a borrower worried about a high rate still needs a second or third quote to know where it lands. Programs also vary by state, so the menu available in Virginia may differ from the one in Tennessee; check with the lender for your property’s state.
- Retail loan officers who stay with the file, which suits borrowers who want one point of contact.
- In-house underwriting, which can keep decisions and questions inside one company.
- Purchase and refinance loans for buyers and owners.
- Down payment assistance offerings, verified current and by state before you count on them.
Setup involves an initial conversation with a loan officer followed by document collection, and the loan team runs the file day to day. Integrations and partner details are on the website. It is less suited to borrowers who primarily want multiple lender prices in one sitting, or who need specialized lending outside standard purchase and refinance. Pricing is quote-based and depends on credit score, loan amount, down payment, program, and state.
Best for: Borrowers who want one national retailer with a relationship-based process.
6. NFM Lending
NFM Lending is a national retail mortgage lender organized around branch-based loan officers. If you value having a named officer in an actual office, it offers that structure across a broad product menu.
The standout versus others here is the combination of branch-level officers and range: its menu reportedly spans conventional, FHA, VA, and USDA loans, with purchase and refinance options, and it has offered online application tools. Verify each of those details on its website as of publication, since program lists and tools change.
The limitation is the same one that applies to every direct lender in this group: a single lender’s pricing. If you are working on a rate that feels too high, an NFM Lending quote is best treated as one data point. You would need to collect other Loan Estimates yourself to see whether a different rate sheet beats it, and doing that across several lenders costs time, and sometimes several hard credit pulls if you are not careful about timing.
That last point is worth stating clearly, because it is a common misconception that every inquiry hurts your score equally. Scoring models generally treat multiple mortgage inquiries within a short window as one, but the window varies by model and not every lender’s process is identical. Ask each lender how and when it will pull credit before you authorize anything.
- Branch-based loan officers who can handle questions in person or by phone.
- A broad program menu, so a buyer comparing FHA, VA, USDA, and conventional can stay with one lender.
- Purchase and refinance options for both new buyers and owners.
- Online application tools, where available, to speed up document collection.
Setup is a mix of an officer conversation and online paperwork, with the branch team running the file. It is a weaker fit for borrowers who want several lenders compared for them rather than doing it themselves. Pricing is quote-based and moves with credit, down payment, program, and property type.
Best for: Borrowers who want a branch-based officer and one more quote to compare.
Matching the Right Option to Your High-Rate Situation
Duane Buziak’s read is that no option on this list removes a high-rate environment. What changes is how many prices you see before you decide.
- Veteran with an existing VA loan: start with an IRRRL analysis. Veterans United Home Loans specializes in VA lending, and Duane Buziak also prices VA loans across wholesale lenders, so getting both is a sound comparison.
- First-time buyer who wants local help: Guild Mortgage and NFM Lending both lean on branch-based officers, and Movement Mortgage offers a relationship-driven retail path.
- Borrower who wants multiple lender quotes without a hard credit pull: Mortgage Mastermind by Duane Buziak, through its NoTouch Credit Pull and wholesale access.
- Borrower who wants the fastest self-serve process: Rocket Mortgage, with a second quote in hand.
How the Structures Compare
| Feature | Duane Buziak | Typical Direct Lender | Why It Matters |
|---|---|---|---|
| Rate sheets | Hundreds of wholesale lenders | One internal rate sheet | More prices on the same file can surface a lower rate or cost. |
| Credit pull at the start | Soft-pull pre-approval (NoTouch Credit Pull) | Varies by lender; ask before authorizing | Fewer early hard inquiries while you compare. |
| Program range | Purchase, refinance, VA, USDA, renovation, commercial, specialized | Usually a defined retail menu | Unusual files need a lender that fits them. |
| Application path | Consultative, strategy built around you | Single application path, often digital | Self-serve speed versus guided comparison. |
| Geographic reach | VA, FL, TN, GA, DC, NC, SC, MD | Often nationwide | Availability depends on where the property is. |
Questions Borrowers Ask About High Rates
Is the mortgage rate the same at every lender?
No. Each lender sets its own pricing, and wholesale lenders price differently from each other, so the same borrower can receive different rates and costs on the same day.
What is the difference between a mortgage broker and a direct lender?
A direct lender funds loans from its own rate sheet. A broker can place a loan with many lenders. Duane Buziak operates as both a broker and a lender, depending on the file.
Do I have to refinance right away if I buy at a high rate?
No. Refinancing later can help if rates fall, but it carries closing costs, so it only pays off if you keep the new loan long enough to recover them.
What are discount points?
Prepaid interest, with one point equal to 1% of the loan amount, that lowers your rate. They make sense when you will keep the loan past the break-even point.
What is a lender credit?
A credit toward closing costs in exchange for a slightly higher rate. It reduces cash at closing but raises the monthly payment.
Does comparing lenders hurt my credit?
Mortgage inquiries made in a short window are generally scored as one, but not every inquiry hurts the same. A soft-pull pre-approval avoids the hard inquiry up front.
How do I compare offers accurately?
Use the Loan Estimate each lender provides, which the CFPB explains. Compare rate, points, credits, and total closing costs together, not the rate alone.
Can a broker guarantee the lowest rate?
No. Shopping more rate sheets improves your chances, but no one can guarantee the lowest rate on every day.
A State Data Point: Virginia
The FHFA’s 2026 conforming loan limit announcement sets the baseline at $806,500 and the high-cost ceiling at $1,249,125. In Virginia, parts of Northern Virginia sit in high-cost areas, while most of the state falls under the baseline, so confirm your county’s limit before choosing a program. Virginia borrowers can also check the state housing finance agency, Virginia Housing, for current homebuyer programs, and verify eligibility there.
Ready to experience the award-winning service that earned us VA Broker of the Year and recognition as a top 1% nationwide mortgage broker? Schedule your no-pressure consultation today and discover how our customized financing strategies across VA, FL, TN, and GA can help you achieve your homeownership or investment goals with credit-safe inquiries and expert guidance every step of the way.

